Is your pension plan making a rate bet?
Corporate pension plan liabilities are sensitive to changes in long-term interest rates, creating a key risk for the sponsor’s balance sheet and other financials. Like bond prices, pension liabilities shrink as interest rates rise and increase as interest rates fall. Plan sponsors use fixed income assets to manage this risk, but for an underfunded plan, positioning that provides more interest rate protection than needed can limit the benefit of rising rates and slow progress toward full funding. With long-term rates rising again in 2026, plan sponsors may want to examine whether their hedging strategy is providing the intended protection or making an unintended interest rate bet.
Hedge ratio explained
To offset unexpected swings in pension liabilities due to changes in interest rates, plan sponsors typically allocate a portion of their assets to fixed income. The conventional measure of the interest rate protection provided by the portfolio is the hedge ratio, which compares the interest rate sensitivity of the plan’s portfolio with the interest rate sensitivity of its liabilities. A hedge ratio of 100% means that, in aggregate, the portfolio is expected to offset the impact of interest rate changes on the liabilities. Plans maintain different levels of hedging depending on the portion of assets invested in fixed income, the duration and structure of those investments, and the plan’s funded status.
Consider hedge effectiveness
Not all hedge ratios are equal. The total hedge ratio assumes that interest rates move up and down in a parallel fashion across the yield curve. In practice, short-term rates are driven largely by Federal Reserve policy, while long-term rates are influenced by other economic factors. Rates at the front, middle and long end of the curve rarely move in sync. To avoid unexpected pension financial outcomes, it is important to understand how effective the hedging strategy is at all parts of the curve, not just in aggregate. Even when the fixed income portfolio matches the liability in total, it can remain materially overhedged in some areas of the curve and underhedged in others. When rates move differently across the curve, these mismatches can cause assets and liabilities to move by different amounts, creating unexpected changes in funded status.
A 100% aggregate hedge can mask significant mismatches
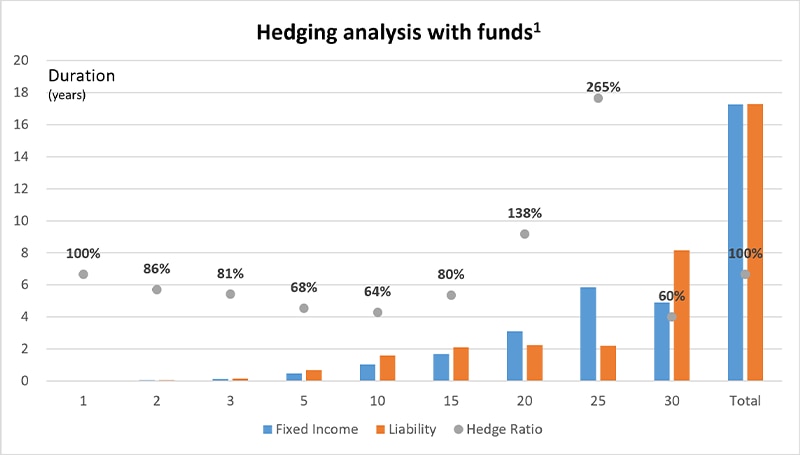
View accessible version of this chart.
The fixed income portfolio matches the liability in total, but the level of interest rate protection varies considerably across the yield curve. A more consistent hedge would maintain the selected target across the curve, reducing the potential for unexpected funded status outcomes when the shape of the curve changes.
Overhedging is a rate bet
Some plans concentrate a significant portion of their fixed income exposure at the long end of the curve. This may be intentional, through strategies sometimes called “capital efficient” hedges, or unintentional, through bond funds that are not designed around the plan’s liabilities. In either case, the fixed income portfolio may be substantially overhedged at certain points on the curve, effectively creating a bet that long-term rates will fall.
Many sponsors may not view their liability hedge this way, but the impact becomes visible when rates rise. We have observed plans with fixed income exposure at long maturities that significantly exceeded the corresponding liability exposure, in some cases by more than three times. When rates rose sharply in 2022, these positions contributed to funded status declines. Rising long-term rates in 2026 have again created an environment in which these strategies may work against the plan. Rather than fully benefiting from declining liabilities, a plan may experience larger losses in its fixed income assets that exceed the decline in its liabilities.
For a typical midsize pension plan, this type of positioning can mean giving back tens of millions of dollars in funded status gains that might otherwise have been retained. That loss of progress can delay full funding and the opportunity to further reduce pension risk.
Guided philosophy
For an underfunded plan, rising interest rates can be one of the levers that help close the funding gap. Moving to a full hedge too early, or overhedging, can reduce that potential benefit. As funded status improves, a glidepath can provide a disciplined signal to gradually purchase additional fixed income and protect more of the progress already achieved.
The appropriate hedge ratio will vary based on the plan’s funded status, objectives and overall strategy. Whatever target is selected, the fixed income exposure should be aligned consistently with the liability across the yield curve rather than concentrated at the long end. This allows an underfunded plan to retain the potential benefit of favorable interest rate movements while establishing a clear path for locking in gains as it approaches its funding goals.
Accessible Version of Chart
Hedging analysis with funds[1]
| Duration | 1 | 2 | 3 | 5 | 10 | 15 | 20 | 25 | 30 | Total |
| Fixed Income | 0 | 0.1 | 0.1 | 0.5 | 1.0 | 1.7 | 3.1 | 5.9 | 4.9 | 17.3 |
| Liability | 0 | 0.1 | 0.2 | 0.7 | 1.6 | 2.1 | 2.3 | 2.2 | 8.2 | 17.3 |
| Hedge Ratio | 100% | 86% | 81% | 68% | 64% | 80% | 138% | 265% | 60% | 100% |