- Many banks, including PNC, require you to be at least 18 years old to open an account on your own.
- Children and teens may open accounts with a parent or guardian as a co-applicant.
- Account options for minors include custodial accounts, joint accounts, teen or student checking accounts, and children’s savings accounts.
From young children managing their allowances to teens earning their first paycheck, there’s nothing quite like hands-on experience to teach a child financial responsibility.
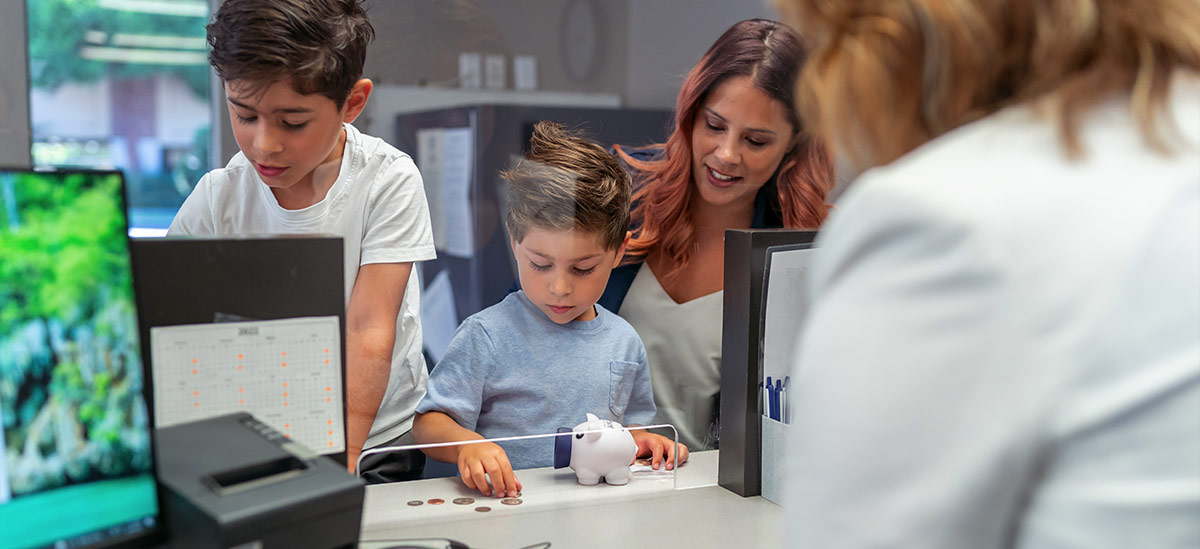
A trip to the bank to open a checking or savings account is a major milestone. But how old does a child have to be to open a bank account? The answer may surprise you.
While children typically cannot open an account on their own until they’re 18, there are several ways to give minors access to a bank account.
Why Are There Age Restrictions for Bank Accounts?
In most states, individuals under age 18 aren’t able to enter into legally binding contracts.1 Since opening a bank account requires signing a contract, minors must have a responsible adult to sign for them. This limitation also creates a layer of protection. Adult involvement typically gives younger account holders guidance and supervision, potentially reducing the risk of mismanaging funds.
Bank Account Options for Minors
Many banks provide multiple options for children and teens to have access to a bank account. Each comes with different levels of control and flexibility.
Custodial Accounts
A custodial account is opened by a parent or guardian on behalf of a child. The adult has full control over the account until the minor reaches adulthood, which is typically at age 18, 19, or 21, depending on the state. At that point, the child becomes the full owner of the account and is free to use the funds however they choose.
Custodial accounts are often used for long-term savings goals, such as for the minor’s first car or college expenses. This account structure ensures that the minor listed on the account ultimately receives the funds. However, depending on your goals, the immediate and unregulated access to the account at the age of majority may be a significant drawback.
Joint Accounts
A joint account lists both the minor and the adult as co-owners. Both have full access to the account, including the ability to deposit and withdraw funds. Some accounts allow the adult to set spending alerts or limit the minor’s activity, allowing for some supervision.
A joint account may work well for teens who are ready to take on more financial responsibility but still benefit from having a parent or guardian keep an eye on things. Since both parties have access, joint accounts may also provide greater flexibility. However, giving a minor direct account access could also increase the chances of mismanagement.
Teen or Student Checking Accounts
Teens and young adults may benefit from a teen or student checking account. These typically come with basic features, including a debit card, ATM access, and online or mobile banking. They may also have reduced fees and guardrails to help younger account holders avoid common problems.
For example, PNC’s Simple Checking account doesn’t require a minimum deposit when opened online, does not have overdraft fees, and waives the monthly service charge for customers under 25 or with qualifying direct deposit. The mobile app and online banking features also include monitoring and alerts, and quick, easy transfers that can help with money management.
A teen or student checking account requires more financial responsibility. It also gives the account holders real-life experience with making deposits and keeping track of spending limits. An adult co-owner may still be able to set up spending alerts and easily transfer funds into the account.
Children’s Savings Accounts
Some banks offer savings accounts specifically for children. These accounts have built-in parental controls and often come with age-appropriate educational features that are designed to introduce kids to the basics.
PNC’s S is for Savings is one example of a child-friendly account. It includes interactive tools that introduce children to the concepts of saving, spending, and giving with help from their friends at Sesame Street.
Benefits of Giving a Minor Access to a Bank Account
Children who have access to a bank account have the opportunity to build real-world money skills early in life. Rather than learning through theory, they may see how daily decisions affect their account balance. Over time, this may help develop skills such as:
- Decision-making: Deciding when to save and spend, and experiencing the real-life results of these decisions, may create a stronger foundation for managing money in adulthood.
- Consistency: Seeing the impact of making regular deposits into an account may help make saving a habit.
- Accountability: Having their own bank account may encourage children to make more thoughtful choices.
While these benefits don't happen all at once, a bank account creates consistent opportunities for guidance and learning. With regular involvement, these early experiences may help create a strong foundation for better money management skills throughout their lives.
What You Need to Open a Bank Account for a Minor
Opening an account for a minor is a simple process. While the requirements may differ slightly from one bank to another, many require the following:
For the minor:
- Full legal name and date of birth
- Social Security number or Individual Taxpayer Identification Number (ITIN)
For the parent or guardian:
- Government-issued photo ID (U.S. Driver’s license, State ID, passport, or Military ID)
- Social Security number or Individual Taxpayer Identification Number
- Contact information (phone number and email)
While some accounts can be opened online, others may require making an appointment at a local branch. Depending on the account, you may also need an initial deposit.
How to Choose the Right Account for Your Child
When choosing an account for your minor child, consider their age, maturity, and current needs. For example, a six-year-old may benefit from the educational tools that come with a child’s savings account, while a teen with their first job may need a more feature-rich account with debit card access.
As you compare options, also review key factors such as:
- Account fees
- Minimum balance requirements
- Parental monitoring and spending controls
- Overdraft policies
Built-in controls and forgiving policies may also help minors build their balances faster while also reducing the impact of financial mistakes. You may also look for accounts that offer specific features that are important to you, such as an interactive online banking experience, the ability to monitor transactions, and an educational component.
Tips for Teaching Kids Financial Responsibility
It takes time to build good financial habits, and the right guidance can make all the difference. Follow these tips when teaching your kids about money:
- Start with real-world practice: Give children opportunities to use their accounts for small purchases or savings goals.
- Set clear expectations: Talk to your kids about how to make decisions around savings, spending, and giving.
- Review account activity together: Regular check-ins may help reinforce good habits and address mistakes early.
- Encourage goal setting: Saving for a specific item or milestone may make money management more meaningful.
- Set a good example: Letting your children see you making responsible financial decisions may influence their future behaviors.
Keep in mind that small decisions add up over time. Remain consistent and encourage open conversations about financial matters.
Setting Up Your Child for a Strong Financial Future
It’s never too early to set a child up for a bright financial future. By introducing minors to responsible banking, you can help them build confidence and develop smart money habits. Over time, these experiences may make it easier to manage their spending and saving, giving them a strong foundation for growth.