At a Glance:
- Embedded finance now extends beyond payments to payment initiation, account and identity verification, cash visibility, reconciliation, and other treasury services built into everyday business workflows.
- APIs and platform connectors may reduce manual work, improve visibility, and make financial experiences more seamless.
- Businesses can start with one high-impact use case tied to measurable operational or customer outcomes, then expand as needs evolve.
A decade ago, GPS was largely a standalone device. Today, it works quietly inside the apps and services people use every day. Banking capabilities are moving in a similar direction, becoming more integrated into the platforms businesses rely on.
Businesses increasingly expect banking capabilities to be available within the systems they already use. They want to initiate payments, reconcile transactions, and monitor liquidity without moving between operational platforms and banking portals.
That expectation is pushing embedded finance beyond convenience and turning it into a way to help improve operations, strengthen customer experiences, and support growth.
“What began primarily as embedded payments has matured into a broader strategy that allows organizations to integrate financial services across customer-facing and back-office processes,” said Bob May, PNC’s Head of Corporate Embedded Finance. “The result is a more connected, efficient, and intuitive experience for both businesses and their customers.”
What Is Embedded Finance?
Embedded finance brings financial services – such as payments, account verification, identity verification, cash visibility, reconciliation, and treasury capabilities – directly into a business’s products, services, and workflows, including client-facing digital experiences.
Application programming interfaces (APIs) help make those connections possible. They serve as building blocks between banking services and the enterprise resource planning (ERP), treasury, client-built applications, or industry-specific platforms businesses already use. But APIs are only part of the solution.
Depending on the workflow and technology environment, businesses may also use prebuilt connectors, software-platform collaborations, or secure file exchange. Effective embedded finance also requires banking experience, secure infrastructure, and a clear understanding of the process being improved.
“The technology matters, but the experience should feel simple: fewer handoffs, less manual data entry, and faster access to the financial tools or information needed in the moment,” said May.
The market is also expanding quickly. One industry forecast projects the U.S. embedded finance market will grow from $41.34 billion in 2025 to $115.98 billion by 2030 [1].
Reducing the “Swivel Chair” Problem
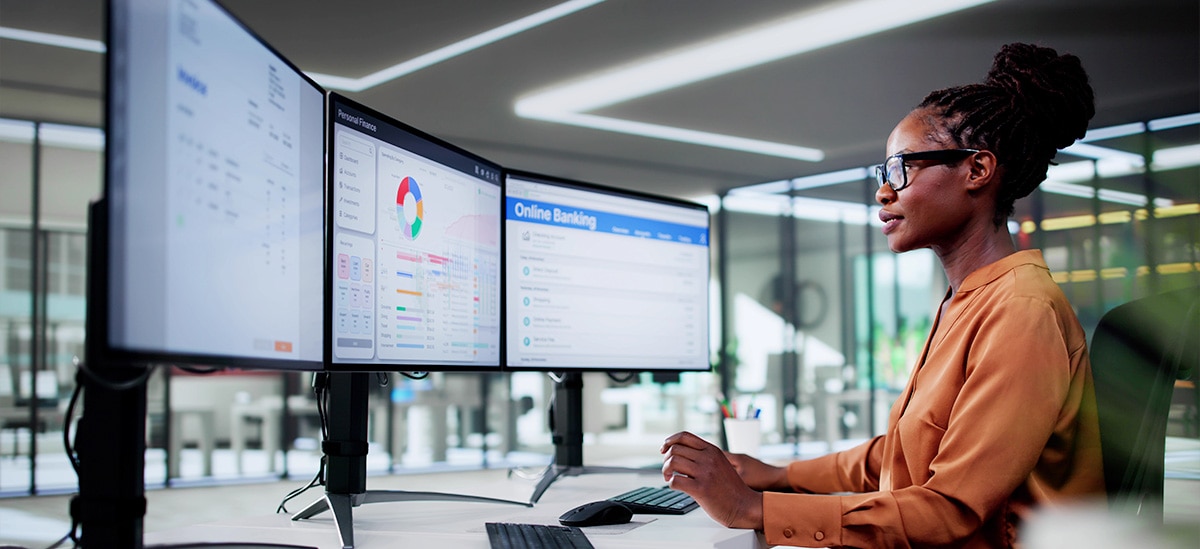
For many treasury and finance teams, a single process still requires moving among an ERP, treasury workstation, accounts payable application, and bank portal.
This constant “swivel” between systems slows work, creates opportunities for error, and makes it harder to see current cash positions. Embedded finance connects banking platforms with business applications so employees may view balances, initiate payments, verify account information before sending funds, reconcile activity, and access reporting within a familiar workflow.
The result is less manual work, greater control through permissions and approvals, and faster decision-making. As expectations for real-time payments, connected platforms, and better financial visibility grow, more organizations are turning to embedded finance to help meet those demands.
Solutions such as PNC’s PINACLE Connect® may integrate banking capabilities with a business’s ERP or treasury management system, helping teams access account information, reconcile activity, and manage payments within the systems they already use. Embedded finance may also extend these capabilities into industry software and a business’s own products, portals, and customer experiences.
Start with a High-Impact Use Case
Effective embedded finance strategies begin with a customer or employee need – not the technology. Where does a delayed payment create uncertainty? Which manual handoff slows the treasury team? What information would help someone make a better decision without leaving the platform they already use?
Strong starting points often involve high transaction volume, frequent errors or exceptions, poor visibility, or significant manual effort.
“Businesses do not need to redesign every financial process at once,” said May. “A practical approach is to launch around one high-impact use case, such as payment initiation, account verification or cash visibility, or automated reconciliation, measure the result against defined operational or customer outcomes, and expand as needs change.”
As embedded finance evolves, businesses may differentiate themselves by placing the right financial capabilities where they create the greatest value.
Ready to Help
PNC can help businesses connect banking capabilities with the platforms they already use and the digital experiences they create for their employees and customers.
Explore PNC’s integrated treasury management solutions to learn how a more connected approach may help streamline financial operations while preserving the security and controls corporate finance teams require.